1 Product Manager, 3 Engineers, 2 Legal advisors, Marketing Manager, additional Fintech strategy leader and operations stakeholders
Defined 0->1 UX vision - I facilitated all major design decisions, led UX critique and research sessions, mentored writers and drove the transition from MVP to MLP.
UX Strategy, Research synthesis, Experience design, Content design, Usability testing, iterative product rollouts and cross-functional alignment
Booking.com wanted to expand into fintech and create a new revenue stream beyond travel.
Launch a B2B cash advance solution to help property partners bridge off-season and emergency cash flow gaps - creating a new revenue stream for Booking.com while strengthening partner loyalty and trust.
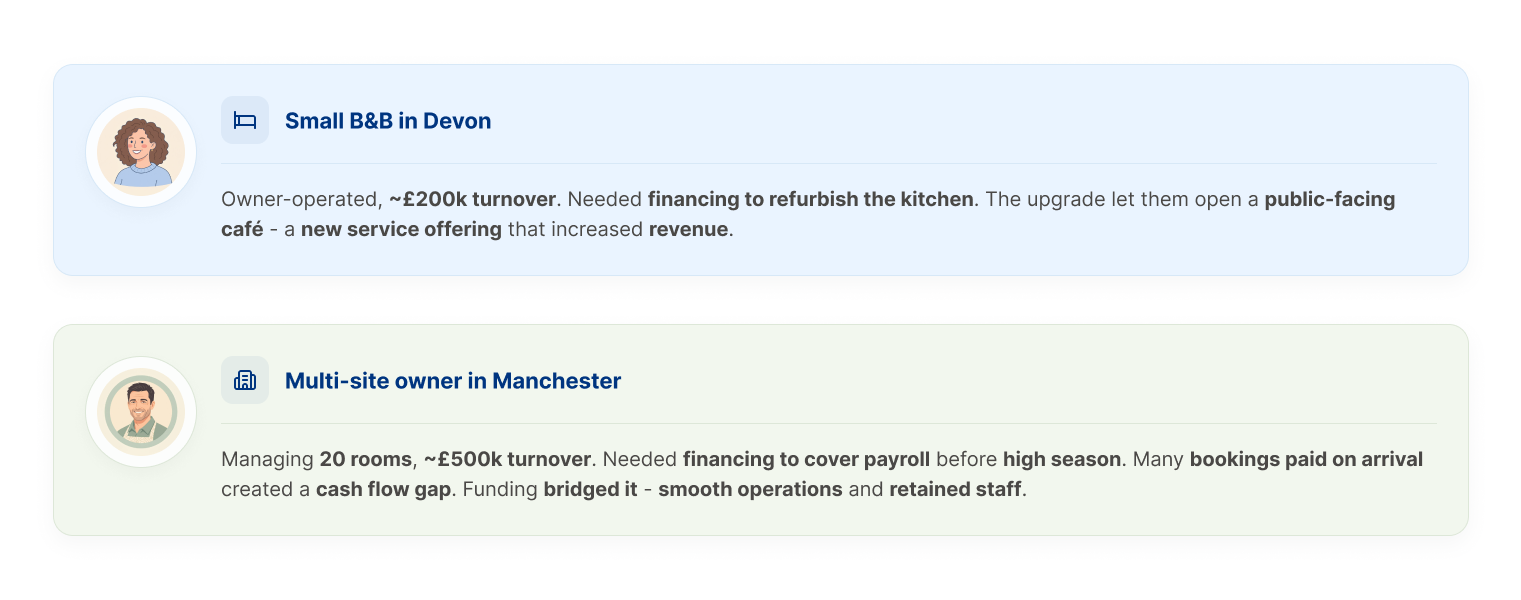
Small and seasonal property partners across Europe and the UK faced cash flow gaps during off-season or emergencies that limited their ability to grow:
To support Booking.com’s accommodation partners, we wanted to give them the opportunity to work with our lending partner(s) to obtain funding that would help them to invest in growing their property or cover business-related expenses, like property upgrades and off-season expenses.
Dream Chasers
- Small operators seeking quick access to capital for growth opportunities or emergencies.
- They struggle with funding, face barriers in accessing capital and are frustrated by slow, non-transparent bank processes.
- They are constant home flippers, i.e., constantly renovating and upgrading multiple properties.

Off-Season Warriors
- Seasonal businesses, like resorts & vacation home owners needed flexible repayment schedules.
- Due to the business seasonality, they required control over when and how repayments are made.
- They had short-term credit needs and depend on flexible, short-term financing to bridge revenue gaps.
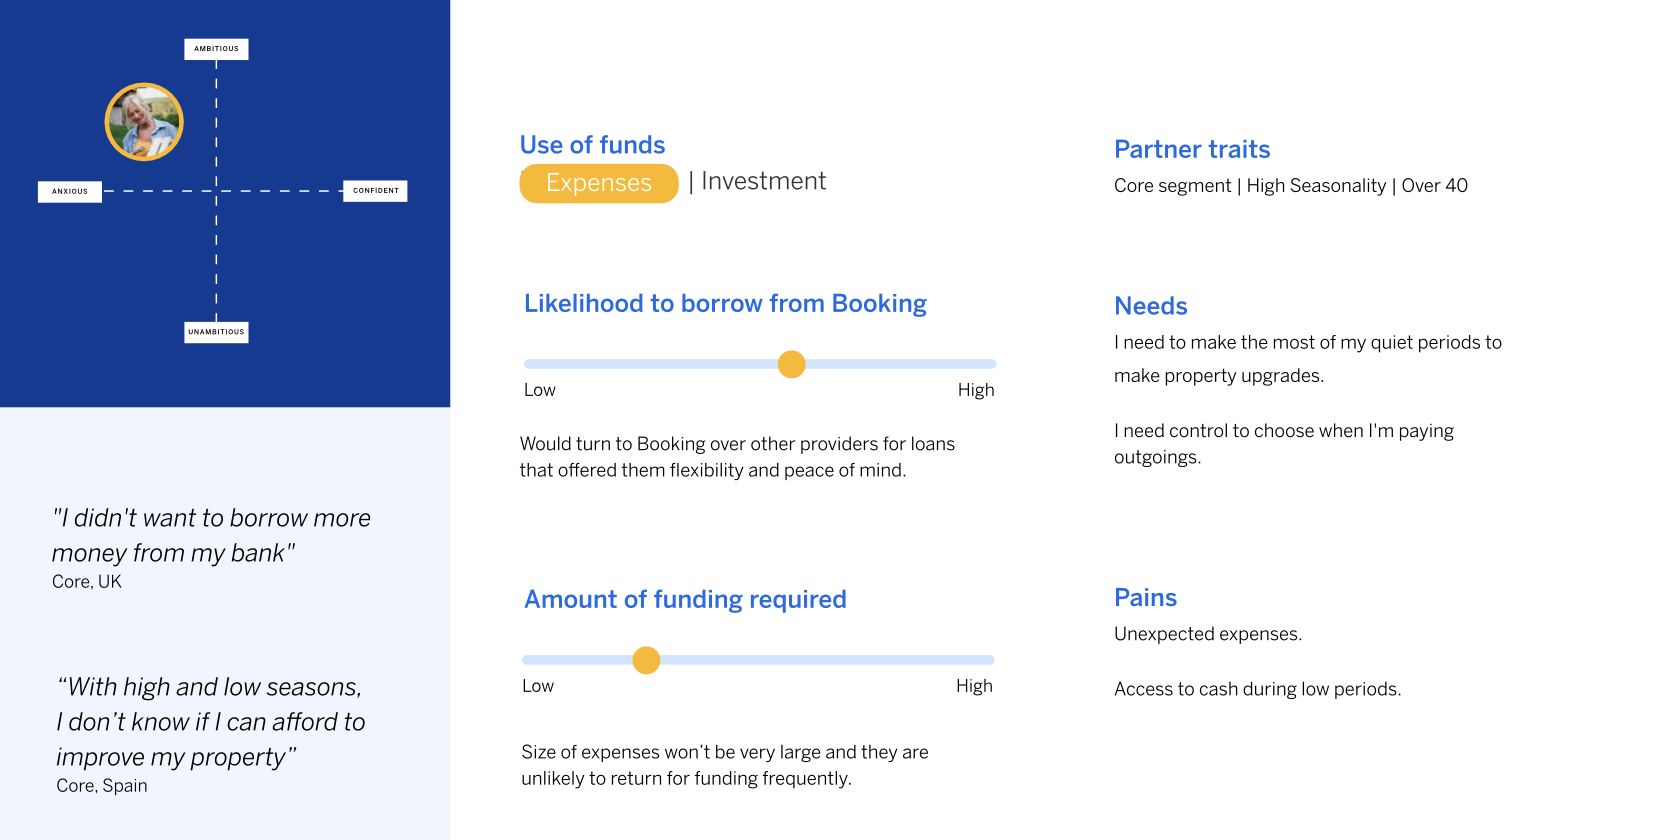
Our partners fall into distinct archetypes, each with unique needs and challenges that shape how they approach our product's adoption and growth.
The whole process consists of two phases:
Phase 1: Understood the market & user segments and collaborated with our fintech vendor to rapidly test the minimum viable product. Partner feedback and early adoption data guided quick iterations on onboarding flows, communication touchpoints, and product messaging.
Phase 2: Evolved from MVP in to building the Minimum Lovable Product (MLP) by enhancing the UX around transparency, repayment tracking, and partner support. Iteratively tested different flows and touchpoints (e.g., banners, dashboards, FAQs) to improve trust and partner adoption.
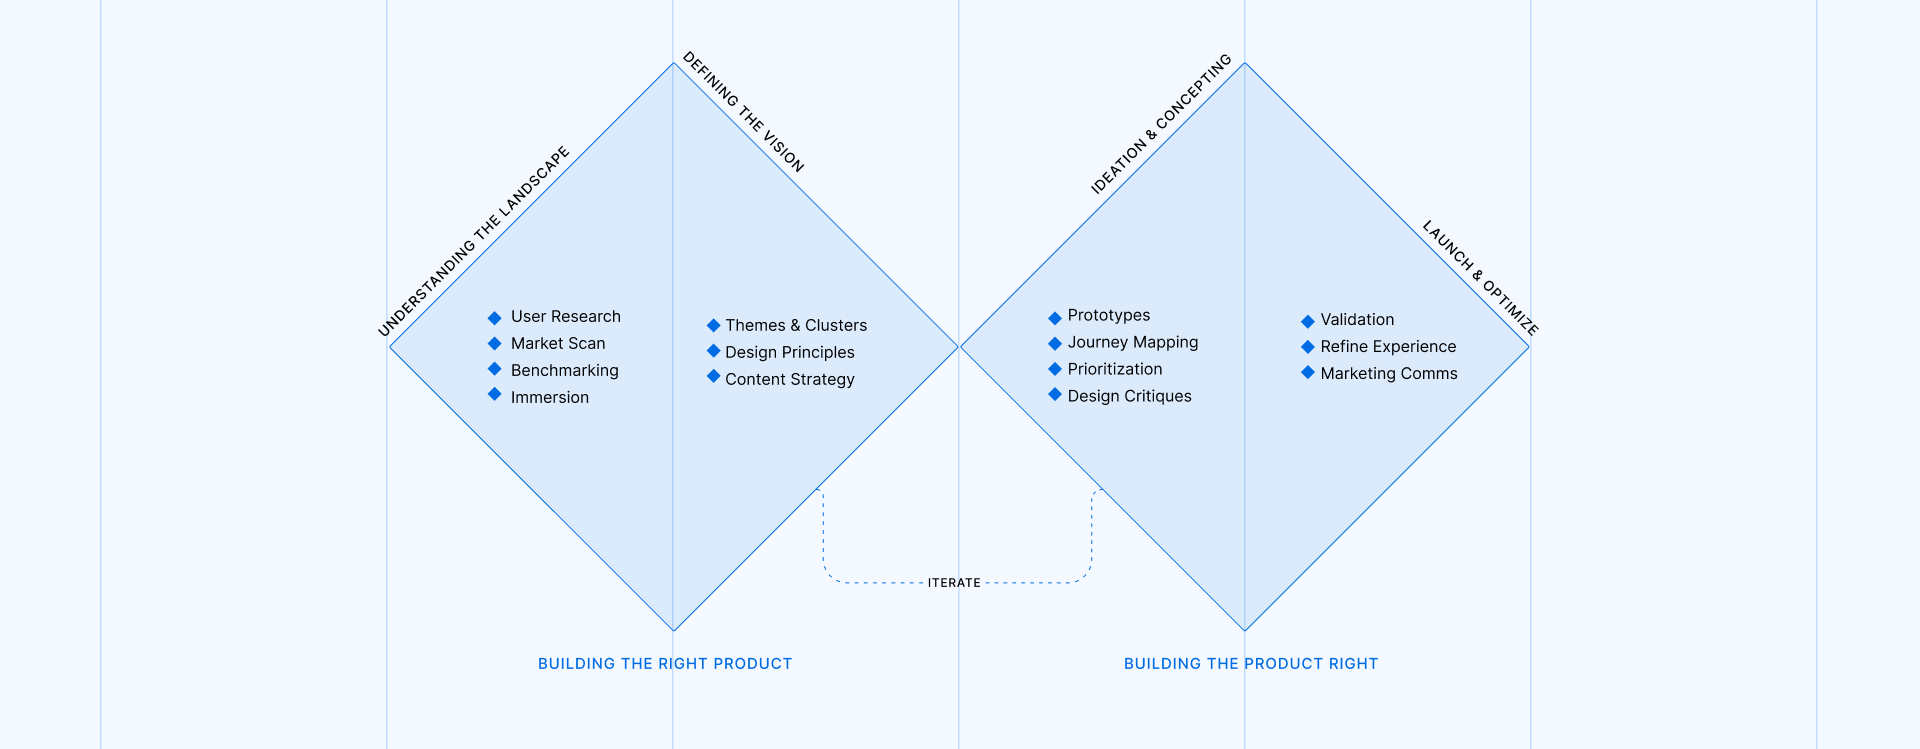
The first phase focused on rapidly testing the minimum viable product (MVP) with a small, controlled group of regional partners.
01
Market & segment understanding
Identified priority segments who faced recurring cash flow gaps (seasonal operators, small B&Bs, sole traders).
02
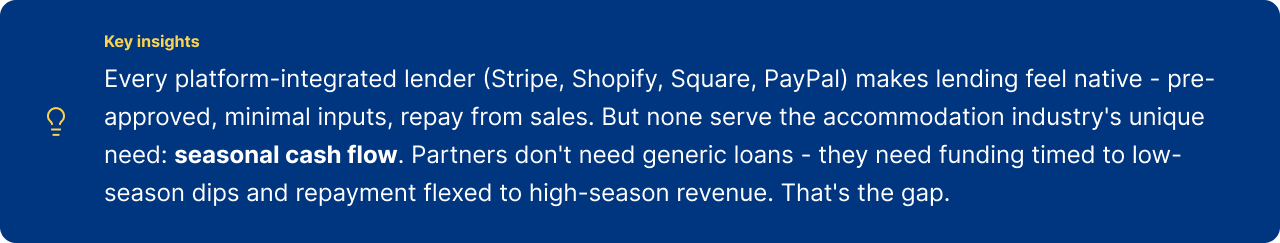
Competitive analysis
Analysed 16 competitors (Stripe Capital, Shopify Capital, PayPal Working Capital, Square Loans, Amazon Lending, eBay/YouLend).
03
Fintech vendor collaboration
Partnered closely with our external financing provider to design flows that met compliance while staying user-friendly. Facilitated rapid ideation workshops with PM, proposition designer, and legal advisors.
04
4. Rapid onboarding
Created lean application and contract experiences, supported by minimal content touchpoints (emails + landing page).
05
Content design
Content was critical with financial terms, one wrong word can break the trust or cause legal implications.
I authored all first drafts on: eligibility messaging, repayment explanations and marketing copy.
06
Feedback loops
Designed feedback loops across partner interviews, behavioural signals, with legal teams and in-product experiments.
Building the team alongside the product - Since there was no dedicated writer initially, so I authored all first drafts. When a writer joined, I coached them by:
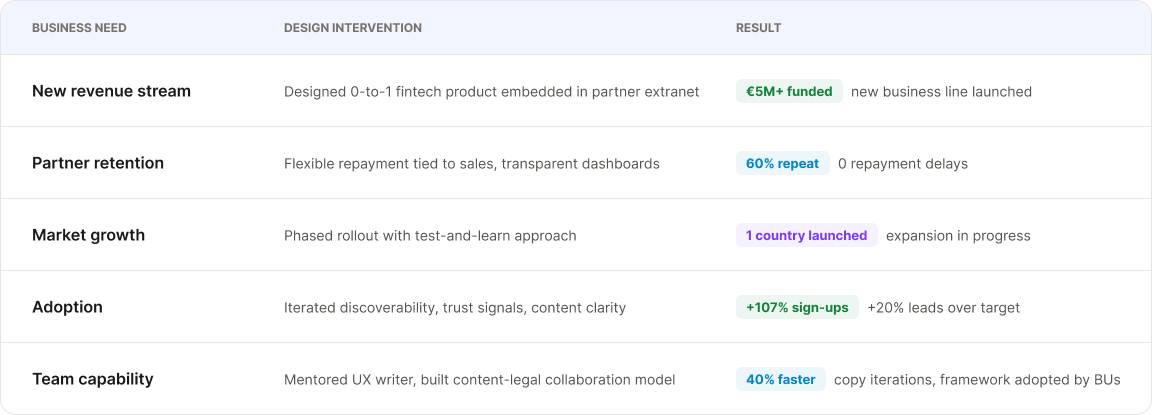
Result: 40% faster iterations, 30% fewer reviews, writer autonomous by month 2. This model became the team default. It didn't just speed up this project. It changed how the team works.
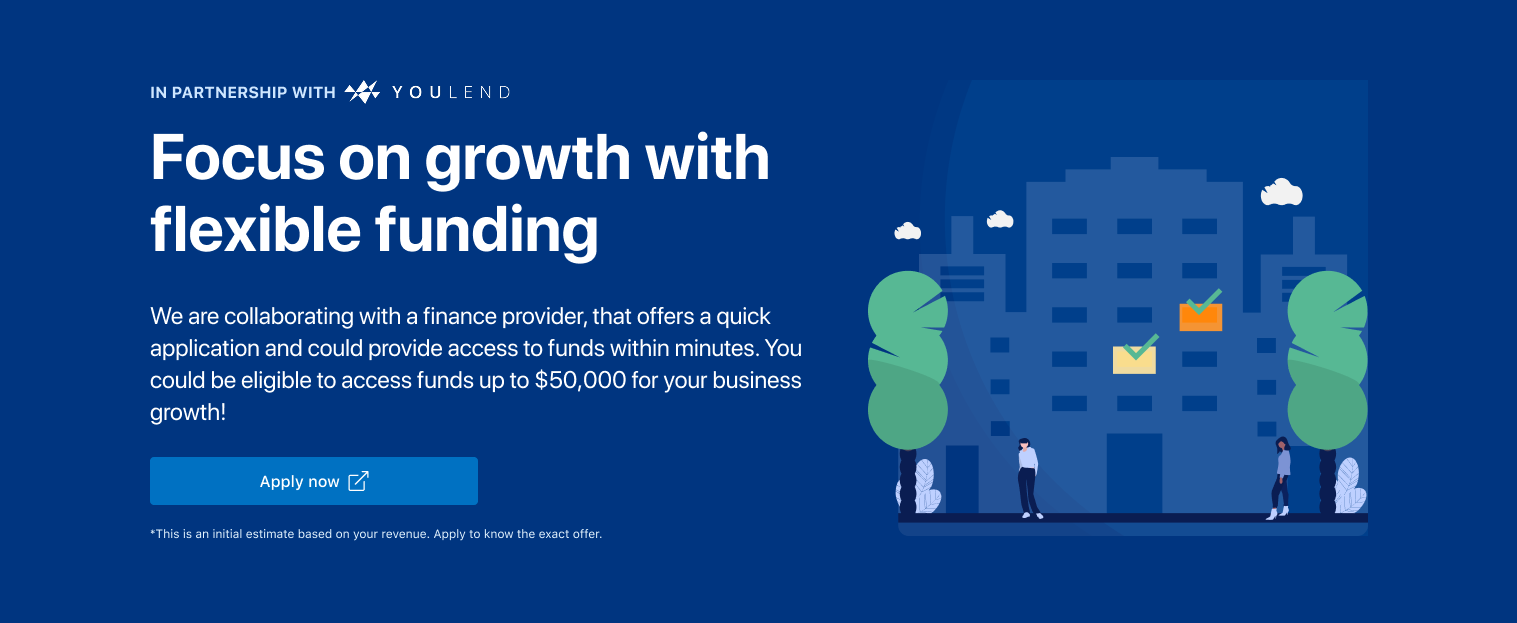
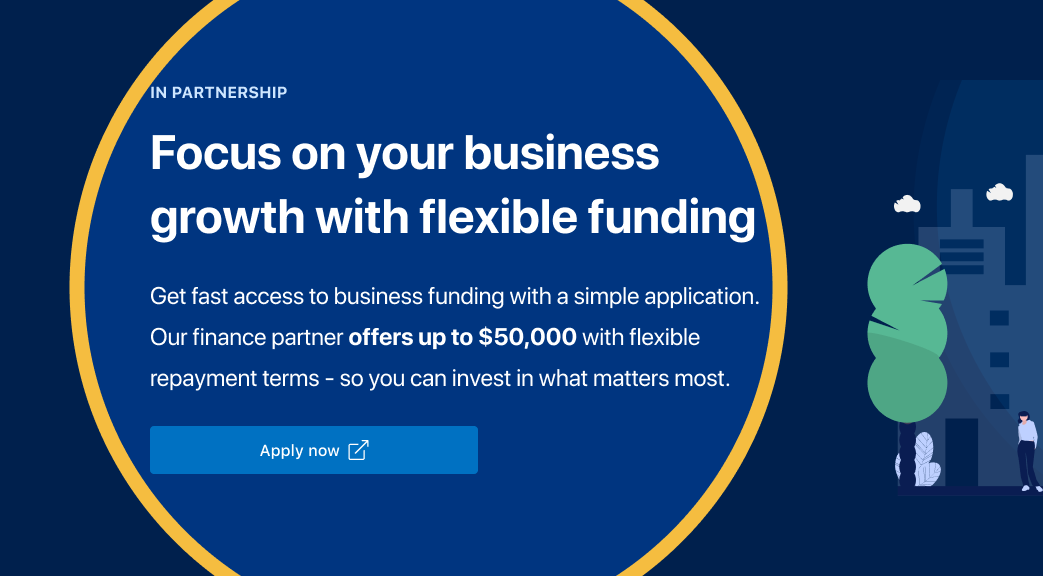
Landing page credibility ~
Problem: Partners had never seen Booking offer financial products. Zero credibility.
Design decision: Lead with value prop ("Focus on your business growth with flexible funding"), show estimated amount upfront, single "Apply now" action.
Why: First impression determines trust. If it feels like spam, partners never click.
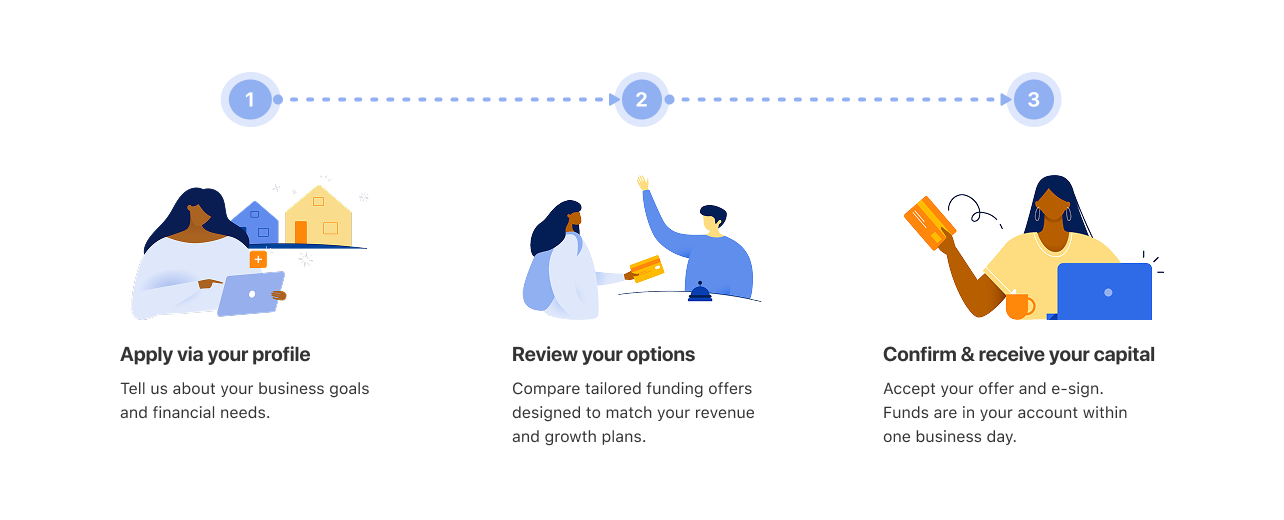
Transparent application process ~
Problem: Financial applications are intimidating. Partners associate them with bank paperwork.
Design decision: Pre-approved amounts based on Booking revenue data. No additional inputs. Integrated into existing extranet.
Why: Every extra field is a drop-off. We had the data - used it to design for scalability.
Readable terms ~
Problem: Legal contracts are unreadable. Partners sign without understanding.
Design decision: Broke contracts into digestible sections. Highlighted key terms (repayment %, total cost, duration).
Why: If partners don't understand what they're signing, trust erodes at the moment it needs to be highest.
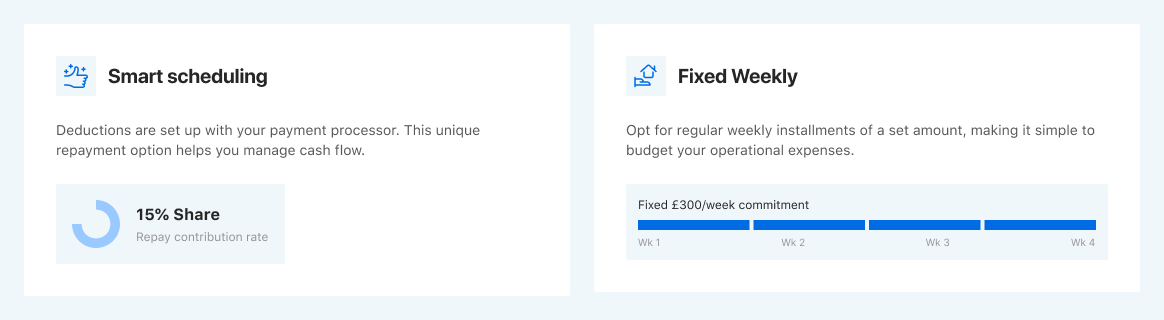
Vendor integration ~
Problem: External lender has own flows and compliance requirements.
Design decision: Co-designed to keep the experience Booking-native. Partners never feel they've left the extranet.
Why: Trust transfers from Booking to the product. Breaking that illusion kills adoption.
I conducted direct partner interviews (8 participants) and surveys to gauge usability and trust of the MVP product.
Behavioral signals (completion rates, repayment trends) were observed as early indicators of adoption.
Partners loved the product overall but 4 gaps emerged out of the MVP research (direct interviews conducted with 7 participants) that defined Phase 2 pain-points:
Clear design learnings for the next phase: need for repayment transparency, richer touchpoints, and stronger trust signals.
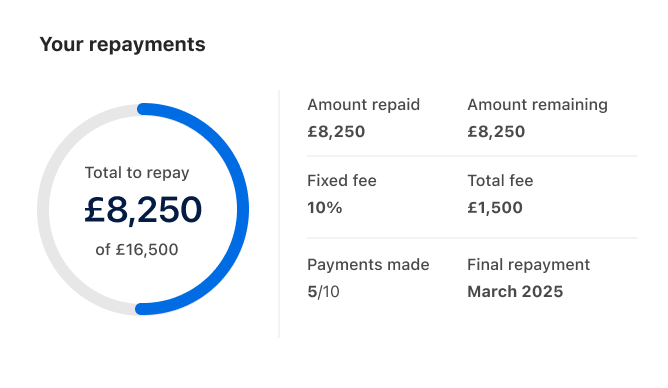
Repayment dashboards ~
Problem: Partners had no visibility into repayment progress. Trusting blindly.
Decision: Built progress trackers showing balance, repayment history, and projected completion date.
Why: Transparency = Trust. If partners can't see their money, they can't trust the product.
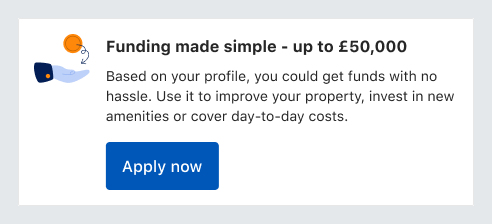
Discoverability:
Problem: Partners didn't know the product existed.
Decision: Iteratively tested banners, dashboard placements, and help content. Found the balance between visibility and not feeling like an ad.
Why: The best product nobody finds is a failed product.
Content strategy revised:
Problem: Despite Phase 1 improvements, legal language still intimidated the users.
Decision: Further simplified with legal. Clarified eligibility. Built supportive messaging around the entire application journey.
Why: Every trust signal compounds. Every moment of confusion costs a conversion.
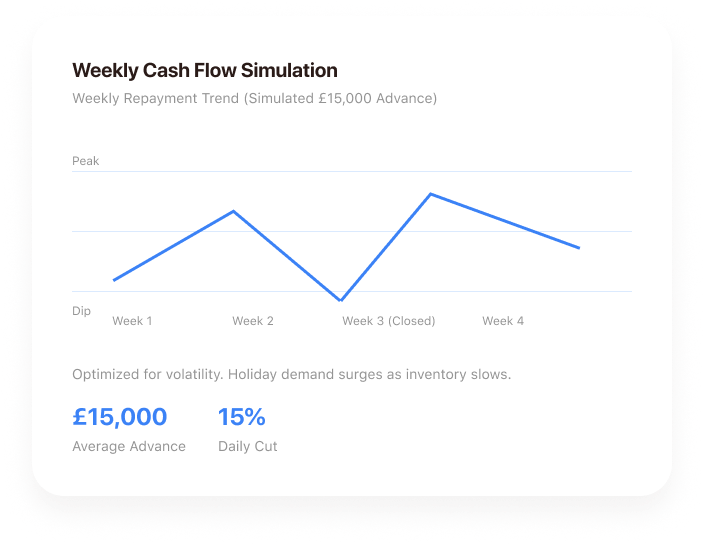
Marketing strategy:
Problem: No playbook existed for marketing a financial product to Booking partners.
Decision: Developed marketing strategy templates - channel mix, messaging framework, partner segmentation for targeting.
Why: This was 0-to-1 not just for the product, but for how Booking markets financial services.
TURNING POINT: The marketing strategy templates I created were adopted by 2 other business units. What started as a tactical need for BCA became a reusable framework - evidence that the thinking scaled beyond the project.